So who’s the real enemy of the people?
/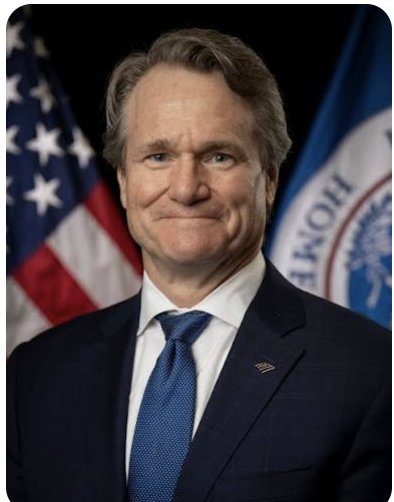
Bank of America CEO Brian moynihan — hey, he’s got an american flag behind him, so you know he’s a patriot
$1.2 Billion Fine to Bank of America
Bank of America can find you if you swiped your debit card in Washington on the wrong day in January 2021. It can find you if your politics carry a whiff of “reputation risk.” What it apparently couldn’t find was $5 billion in suspicious transactions, Chinese money-laundering networks, and a few hundred sanctions violations involving Iran and Russia.
…. On October 13, the Treasury Department dropped the hammer: a $1.2 billion FinCEN penalty, a $750 million civil penalty from the Office of the Comptroller of the Currency credited toward it, and an $11.6 million settlement with the Office of Foreign Assets Control over 475 apparent sanctions violations. All told, roughly $1.21 billion.
…. So what did they do to deserve this? The bank admitted to willfully violating the Bank Secrecy Act. Willfully. Not “inadvertently,” not “due to a regrettable software glitch.” The bank sat on reports of more than $5 billion in suspicious transactions instead of filing them on time. FinCEN said the bank failed to flag activity tied to national security threats, including Chinese money-laundering networks and illicit finance along the southwest border.
The OCC, meanwhile, found that the bank’s monitoring system failed to properly screen trillions of dollars in transactions. Uh, that's trillions. With a T. The sanctions side involved programs targeting Iran, Russia, narcotics trafficking, and global terrorism. That’s a list a compliance department ought to know by heart.
And the best part? The bank had already been warned. The OCC slapped Bank of America with a cease-and-desist order, back in December 2024. More than a year later, regulators said, the breakdowns continued. ….
…. The conclusion here seems inescapable. Bank of America’s surveillance machinery works fine. It just points in the wrong direction. But at whose behest?
Ah, but they can certainly track real enemies of the United States, like the January 6th protesters
After Jan. 6, 2021, according to whistleblower testimony before the House Judiciary Committee, the bank handed the FBI a list of every customer who used a BofA credit or debit card in the Washington area from Jan. 5-7. No warrant. No subpoena. Retired FBI analyst George Hill testified that the bank “data-mined its customer base” with no (publicly acknowledged) directive from the bureau. Bought a sandwich near the Mall that week? [Or bought a MAGA hat anywhere?*] Congratulations, you made the list.
So when the bank wanted to find people who might be Trump supporters, it found them in a hurry. It didn’t need a court order. It didn’t even need to be asked. Chinese money launderers moving billions? Hmm, that one’s tricky.
Then there’s debanking. The same OCC that just fined Bank of America has released a report on the nine largest national banks, Bank of America included. It found that all nine had broad “reputation risk” policies between 2020 and September 2025 that disadvantaged Americans based on their political, religious, or social views. Gould called it “irrefutable evidence” that the nation’s largest banks denied and discriminated against customers and lawful businesses, but ones Democrats disapprove of.
So let’s tally up the scoreboard:
Customers buying coffee in Washington on the wrong week: (found, listed, and shipped to the FBI.)
Conservatives, religious groups, and lawful businesses with the wrong vibes: (flagged as reputation risks).
$5 billion in suspicious transactions:(We'll get to it. )
Chinese money-laundering networks: (Ummm... who?)
Trillions in unscreened transactions: (Well, look, I've been busy).
To be fair, (and I suppose somebody has to be) the money-laundering penalty and the debanking findings are separate cases. Nobody has shown the bank skipped the cartel paperwork because it was busy hunting conservatives. But the contrast tells you everything about priorities. Bank of America built a compliance apparatus with enough horsepower to sweep its customer base for the politically inconvenient. Somehow that same apparatus couldn’t manage the one job the law actually requires of it.
Thought for the Day: A bank that can find your coffee purchase but not a cartel's wire transfer isn't blind. It's choosing where to look.